
November Market Update: A Mover’s Market

It’s a Mover’s Market
As we are now in the final quarter of 2022, we are seeing a slight slowdown in the property market, with fewer properties coming to the market and less urgency from potential buyers to make enquiries or viewings but this is fairly typical for this time of year. Many of our sellers are still accepting good offers but selling times are slightly longer than we have experienced in recent months.
Looking at annual insertions to ESPC.com over the last 5 years (assuming November and December insertions are in line with 2021 figures) the total number of properties brought to the market this year will still be significantly lower than previous years which suggests supply is still short. While supply remains constrained, prices should not collapse, despite what the media is reporting.

It is true that there are negative pressures in the form of more expensive mortgages, but the intense competition and high percentages over home report values required for many properties has been a very big disincentive for many buyers. We believe we will see a better functioning market that allows those wanting to move to do so.
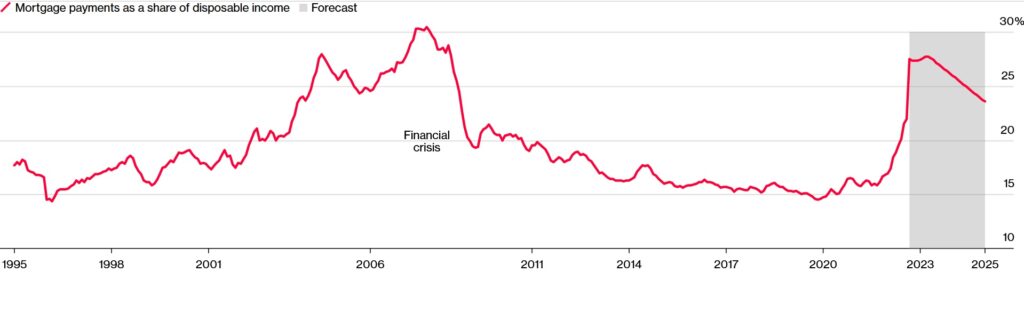
Affordability is back to 2007 levels
The big jump in mortgage affordability is making the news, and it is a concern for many homeowners. Those on variable or tracker rates have already seen mortgage payments rise, but the real shock will come as many fixed rates reach the end of their term.
For the 4 million First-Time Buyers who have bought since March 2009 in favourable times with low interest rates, the recent increases can seem terrifying.
However, research from Bloomberg (see table below) has shown that the percent of disposable income now required to fund a mortgage has returned to the level seen in the housing boom years around 2006/2007. They predict that as the rate increases work through until May next year, it will take 28% of disposable income to fund a mortgage. It has been as low as 15% in recent years but was 30% in September 2007.
Mortgage Rates Are Only Part of the Picture
For example, to buy a £400,000 property with an 80% mortgage when the market was very competitive, a purchase price 10% over Home Report (£440,000) was not unusual, meaning the buyer needed to contribute £120,000 as a deposit to the mortgage amount to finance the purchase (excluding costs and tax).

*At a typical interest rate of 2.5% a mortgage of £320,000 would have cost £1,436 per month. **Now, if it was a 2-year tracker mortgage, monthly payments would jump by £315pm to £1751pm, but there is a good chance that you will not need to make such as substantial offer over the home report, meaning you could save substantially on the deposit or use some of your saved deposit to lower your Loan-To-Value on the mortgage, therefore reducing the monthly cost and making the transaction more affordable. Lenders only lend on the home report value, not on any extra a buyer wishes to pay.
Our view is that there is a positive sense of realism in the market where people keen to move home are able to negotiate good value deals for both their sale and purchase, where they have a skilled solicitor and negotiator working with them.
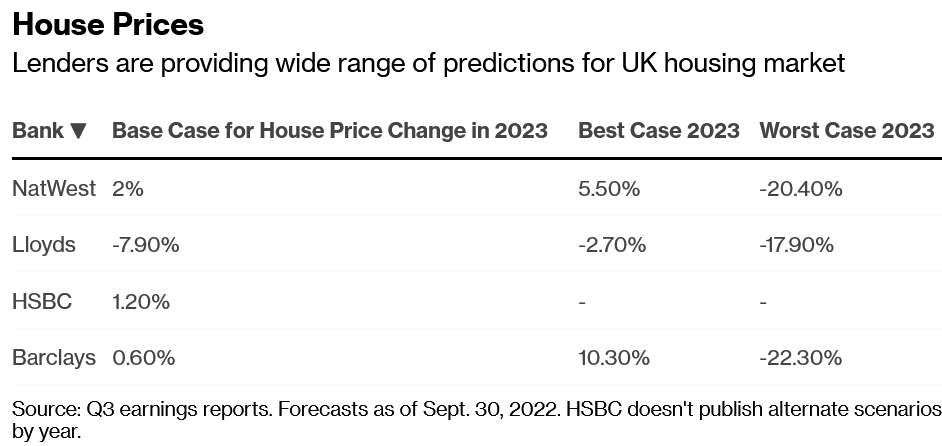
Experts have little consensus in their view for property values next year
There are, however, conflicting opinions on what is going to happen with mortgage rates and the property market as we enter 2023. Lloyds Banking Group have predicted a 7.9% fall in house prices while both Barclays and HSBC feel more positively and predict growth, as the employment market remains strong. Zoopla have noted they believe mortgages rates above 6% are likely to remain throughout 2023.
MoneySavingExpert founder, Martin Lewis, said last week on BBC Radio 4 that now was the time to get independent mortgage advice. He noted that the situation for buyers remains uneven. Many buyers will no longer be able to obtain mortgage products they may have been offered a few months ago but there are lots of buyers who have managed to save large deposits over the lockdown periods. With the slight cooling in prices we expect to see as the market slows in the winter months, buyers will need to pay less above Home Report Value, reducing the amount they need to borrow, making a mortgage more attainable.
Now is the time to speak to and Solicitor and Mortgage Broker
Professional advice has never been more vital. A discussion with an experienced Solicitor Estate Agent, such as Deans, at the outset of your moving journey will make the whole process manageable and clear. We will be able to review Home Reports and past sales for properties you are interested in and offer informed advice on the current market and the best strategy to help you achieve your property aspirations. We have a vast amount of experience buying and selling properties in various market conditions and are dedicated to helping our clients move.
Navigating the mortgage market is even more challenging in this period of uncertainty and change. That is why we work with an independent mortgage and financial advisor who will give you access to a range of products from many different lenders and they will be able to consider the terms of each product and advise what is the most suitable for your personal situation. Mortgage Advisors also often have access to products not available to the customer directly. Just as importantly, they will undertake the application process, guiding you through all the paper work and chasing the lender, to make sure your loan arrives in time, something that has been far from assured recently. We can arrange for you to speak with an independent mortgage advisor, either by phone or in person at our office, to help you understand your budget and affordability for a mortgage and you can also speak with our property team and solicitors, all without charge for the initial advice.
If you have any questions, or would like to consider if now is a good time for you to buy or sell a property, call us now for a no cost or obligation discussion with one of our Solicitors or our Property Director. Call 0131 667 1900 or email mail@deansproperties.co.uk
Your home may be repossessed if you do not keep up repayments to your mortgage. Deans Mortgages is a trading style of Save & Invest Financial Planning Ltd, a fully independent financial and investment adviser, which is authorised and regulated by the Financial Conduct Authority. Save & Invest (Financial Planning) Limited is a company registered in Scotland SC 113651. Our Head Office address is 100, West Regent Street, Glasgow G2 2QD. Telephone 0141 332 8088; Fax 0141 332 7318.